Category

Business & Finance

Comprehensive discussions and expert insights revolving around business & finance trends and best practices.

Oct 31, 2026 • 13 Reads

Can Regular Facade Maintenance Reduce Long-Term Commercial Property Costs?

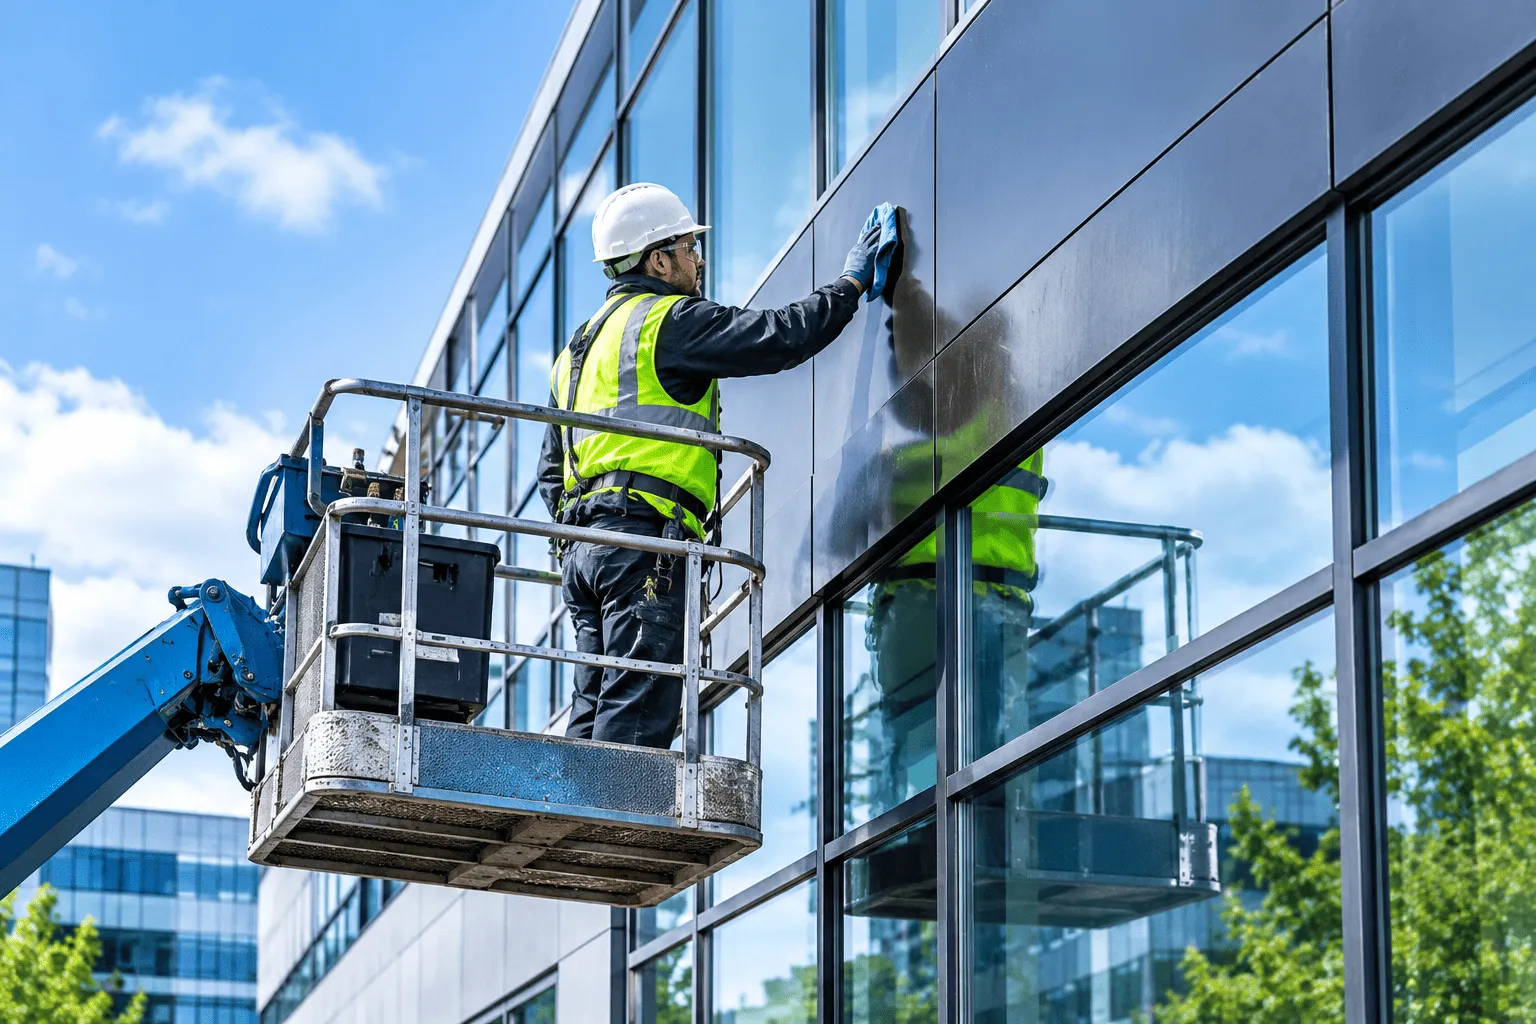
Maintaining a commercial building is more than just keeping it visually appealing. Regular facade maintenance helps shield the structure, stop those very expensive repairs, boost energy efficiency, and keep the property’s long-term worth where it should be. For retail stores, offices, shopping centres and other commercial premises, a well-kept exterior also creates a good first impression for customers, visitors, basically everyone. From architectural steelwork to shopfront cladding, the different pieces of a building’s outer side really need ongoing checking and care. Fixing small defects early can prevent major structural headaches, and it can lower those ongoing maintenance expenses too. Still, you might wonder how much of a difference a planned maintenance strategy can actually make. Why Is Regular Facade Maintenance Important for Commercial Buildings?A building’s facade works like its first line of defence against rain, wind, temperature swings, pollution, and a bunch of other environmental factors. Over time, these things lead to surface breakdown, corrosion, water ingress, and damage to exterior finishes. If you do not do routine inspections, minor problems can quietly grow into costly ones. For example, a small crack in a facade joint can let moisture in, which can then damage internal walls, insulation, and decorative finishes. That’s what usually becomes painful later. Regular commercial facade maintenance helps property owners spot these issues before they need large-scale repairs. It also supports building safety, maintains visual appeal, and helps businesses avoid unnecessary disruption. A preventive maintenance plan usually covers cleaning, checking sealants, inspecting exterior finishes, and taking a close look at structural components for early signs of deterioration. How Can Architectural Steelwork Reduce Structural Maintenance Costs?Quietly, architectural steelwork can really cut down structural upkeep costs. In modern commercial buildings, it does two things at once, supporting structural integrity while also fitting into the contemporary look people want. You see steel components in all sorts of places, like entrance structures, canopies, frames, supports, and even those decorative exterior features that make a façade feel more alive. Even if steel is tough and long-lasting, it still does not love being left alone where moisture, grime, or air pollutants hang around. Over time, if the protective coatings get scratched or somehow fail, corrosion can start. That is why regular inspections matter. They help spot rust early, coating issues, loose connections, and other faults before they turn into bigger problems. When suitable protective coatings are applied and corrosion is handled at an early stage, the service life of those steel elements can be extended quite a bit. Keeping architectural steelwork in good condition also lowers the odds of premature replacement. For property owners, that often means refurbishment budgets stay calmer instead of getting hit by sudden replacement costs. Still, if there is structural damage, it should never be treated like a simple cosmetic thing. Can Shop Front Cladding Improve Durability and Reduce Repair Expenses?   While making commercial premises look better, shopfront cladding also shields the outer surfaces from everyday wear. You can get it in multiple materials, colours, and finishes, so businesses often tune their shopfront design to match their brand identity and vibe.  Still, cladding will slowly lose its edge when it’s left facing harsh weather, urban pollution, accidental impact, or when upkeep is a bit less than ideal. Doing regular checks matters a lot. Early inspections help spot issues before they become a bigger problem. Cleaning the cladding using the right approach, confirming the fixings are secure, and keeping the joints in good shape can help it stay both functional and good-looking.  When the deterioration becomes more obvious, fixing only certain areas may end up being cheaper than replacing the whole installation.  For commercial property owners, keeping shopfront cladding maintained ahead of time helps protect the building envelope, keeps the frontage appealing, and cuts down on refurbishment expenses that could have been avoided. When Should You Consider Shop Front Recoating?When the existing exterior finishes look faded, scratched, weathered, or even a bit discoloured, shopfront recoating can be a pretty practical option. So rather than swapping out the entire shop front, a professional recoating can bring it back to life and add that extra protective layer too. It is often useful for retail businesses that want to modernise their premises without getting into a full exterior replacement type of situation. Recoating can bring a few benefits, like lower refurbishment costs: restoring suitable existing surfaces may be less expensive than replacing them outright. Then improved appearance, because fresh coatings help the shopfront look cleaner and more professional overall. Plus surface protection, since the right coating systems can help defend against weathering and corrosion. And reduced disruption: depending on the job, shopfront recoating might be completed with less disturbance than larger replacement work. Of course, whether recoating really works well depends on things like correct surface preparation, choosing suitable coating systems, and getting the application done professionally. Any damaged substrate, corrosion, or loose components really should be dealt with before new coatings go on. How Does Curtain Wall Repair Prevent Expensive Building Damage?Commonly, curtain wall repairs are seen on modern offices, commercial developments, and retail buildings. These non-load-bearing exterior systems usually rely on glass, metal framing, seals, and connections, all designed to protect the building from external conditions. Over time, though, sealant deterioration, damaged glazing components, loose fittings, and water leaks can start undermining curtain wall performance. If those issues are left alone, moisture can end up getting in, and that can then damage internal finishes, insulation, or whatever sits behind the facade. Timely curtain wall repair helps restore the system’s performance and stops minor defects from turning into bigger, more expensive remedial work. Depending on what is wrong, repairs may include replacing failed sealants, sorting out damaged components, correcting localised water ingress, or repairing deteriorated framing finishes. Regular inspections matter a lot too, especially for buildings with lots of glazing, where leaks and defective joints can be tricky to spot from inside. And since curtain wall repairs can involve working at height, along with specialist glazing parts, they really should be carried out by appropriately qualified professionals. Can Facade Maintenance Increase Commercial Property Value? Honestly, a clean, maintained exterior tends to boost the way the place looks, and that often feeds into how tenants, customers, investors, and prospective buyers actually think about the property. When the surface feels looked after, it can seem more reliable, like the whole asset is being managed properly.On the other hand, if you can see deterioration, it can quietly turn into more worries about hidden defects or about what repairs might still be coming later. But if maintenance is documented, and there’s proof of refurbishment happening on time, it gives a clearer story to anyone reviewing the building.Plus, taking care of architectural steelwork, fixing curtain wall defects, and restoring shopfront finishes can help keep both the building’s performance and its appearance on track. So, while maintenance by itself never offers a full guarantee of higher property value, it can support asset preservation, lower the odds of worsening conditions, and improve the overall presentation of the building.Conclusion Regular facade maintenance is a fair and practical way to handle the long-term cost of commercial property. By catching defects early, owners can reduce the likelihood of bigger repairs later, protect important building elements, and keep the exterior looking professional, as it should be.  From architectural steelwork inspections and shopfront cladding upkeep to shopfront recoating and curtain wall repair, each little task builds toward a more efficient maintenance plan.  Instead of waiting until visible damage turns into a major issue, commercial property owners should prioritise planned inspections and get timely professional repairs in place. 
A
Aleksandra Palmer
Oct 26, 2026 • 20 Reads

Maintenance Considerations for GE High Voltage Gate Input Modules

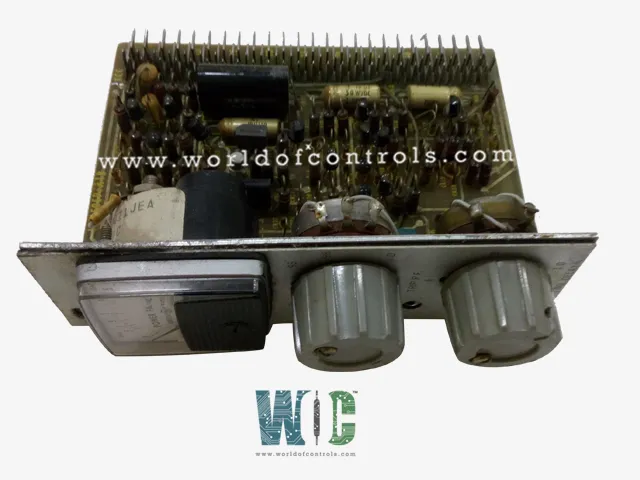
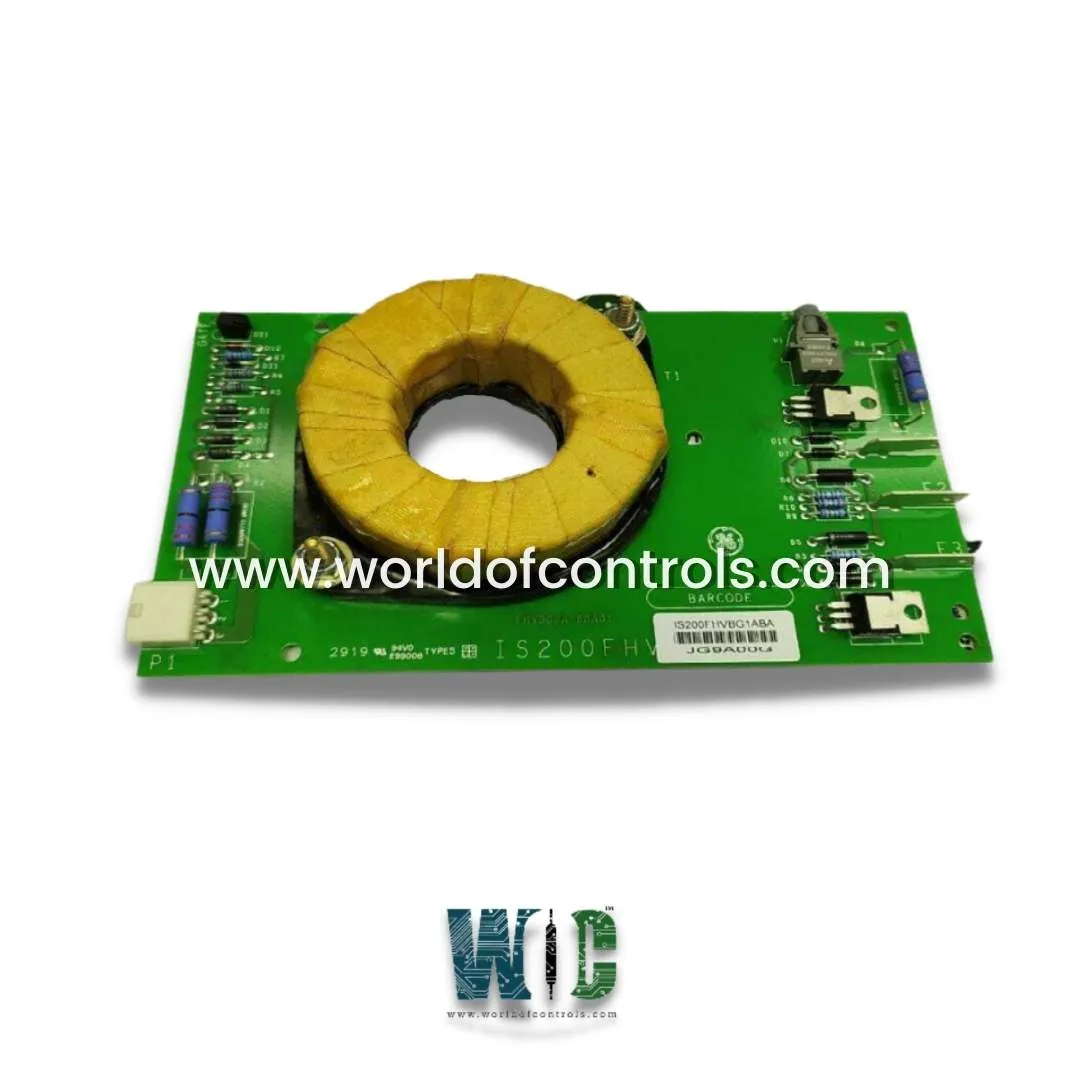
IntroductionReliable turbine operation depends on the performance of electrical control systems, power conversion equipment, and monitoring components. In gas and steam turbine power plants, these systems support essential operations such as turbine startup, generator excitation, and electrical power management. High voltage gate input modules play a role in certain industrial control systems by supporting signal monitoring and communication between control hardware and power electronic equipment.In the turbine industry, GE high voltage gate interface technology is associated with specialized control boards used in industrial power conversion systems, including static starter applications. Proper maintenance of these components helps plant personnel identify potential electrical faults, maintain system reliability, and reduce unplanned downtime.Understanding High Voltage Gate Input ModulesFunction in Turbine Control SystemsHigh voltage gate interface modules form part of the electrical control architecture used in selected industrial power conversion applications. These modules support the interface between control electronics and semiconductor switching devices, such as silicon-controlled rectifiers (SCRs).SCRs regulate high-power electrical currents and are commonly used in static starter systems that help accelerate large turbine-generator drive trains during startup. Gate interface and monitoring circuits assist the control system in managing switching operations and monitoring relevant electrical conditions.Depending on the system configuration, these interfaces may also support cell voltage monitoring and fault detection. Reliable operation is important because electrical abnormalities within the associated power conversion equipment can affect startup performance and overall plant availability.Importance of Preventive MaintenancePreventive maintenance helps identify deteriorating connections, contamination, component damage, and other potential problems before they develop into significant failures. A structured maintenance program also improves troubleshooting efficiency, supports safer operations, and helps maintenance teams plan repairs and replacement activities.Key Maintenance Considerations1. Visual Inspection and Environmental ConditionsRegularly inspect the module and its surrounding control cabinet for dust accumulation, moisture, corrosion, discoloration, and signs of overheating. Ensure that ventilation paths remain unobstructed and that operating temperatures and humidity levels meet the manufacturer's specifications.Pay attention to connectors, circuit board surfaces, and visible components. Burn marks, unusual odors, or evidence of electrical arcing should be investigated by qualified technicians. Cleaning should follow approved procedures to prevent electrostatic discharge or damage to sensitive electronic components.2. Electrical Connections and WiringLoose connections, damaged insulation, and deteriorated terminals can cause intermittent signals or electrical faults. Inspect accessible wiring, connectors, and grounding arrangements according to the applicable electrical drawings and maintenance instructions.Because these modules may interface with high-voltage circuits, maintenance must only be performed after the equipment has been placed in a safe condition. Follow site isolation procedures, lockout/tagout requirements, and approved methods for verifying the absence of hazardous voltage.Never disconnect or reconnect components while energized unless an explicit, manufacturer-approved procedure permits the activity.3. Fault Monitoring and DiagnosticsReview control-system alarms, event logs, and diagnostic indicators for recurring problems involving gate signals, semiconductor switching devices, cell voltage monitoring, or associated power conversion equipment.When a fault occurs, investigate the complete circuit instead of automatically assuming that the interface module is defective. Possible causes include wiring problems, faulty semiconductor devices, abnormal electrical conditions, or issues with related control hardware.Document alarm codes, operating conditions, inspection results, and corrective actions. This information helps maintenance teams identify recurring problems and improve future troubleshooting.4. Functional Testing and VerificationAfter maintenance or component replacement, qualified technicians should perform the inspections and functional checks specified in the applicable OEM documentation. These may include checking connections, reviewing diagnostic indications, and confirming that the associated control system reports the expected equipment status.Electrical testing should use approved procedures and appropriately rated instruments. Avoid applying unauthorized test voltages or changing protection settings, as these actions may damage equipment or compromise system safety.5. Spare Parts and Replacement PlanningMaintaining access to compatible replacement components is important for turbine facilities operating industrial control systems over extended service periods. Before replacing a module, verify its exact identification, hardware revision, system compatibility, and configuration requirements.For obsolete or difficult-to-source components, evaluate refurbishment or replacement options with qualified suppliers and engineering personnel. Proper spare-parts planning can reduce delays during scheduled maintenance and unexpected outages.Best Practices for Long-Term ReliabilityA successful maintenance strategy combines scheduled inspections, condition-based monitoring, accurate documentation, and trained personnel. Inspection intervals should reflect operating conditions, equipment criticality, site experience, and manufacturer recommendations.Maintenance teams should also review historical alarms and repair records to identify recurring patterns. Standardized checklists, clear reporting procedures, and appropriate staff training can improve consistency and help prevent repeat failures.ConclusionGE high voltage gate input modules support important interface and monitoring functions in selected industrial power conversion and turbine-related applications. Their reliability depends on suitable environmental conditions, secure electrical connections, effective fault diagnosis, and correct replacement practices.By implementing preventive maintenance procedures and following applicable manufacturer documentation, turbine industry professionals can improve equipment reliability, minimize avoidable downtime, and support safe, efficient power plant operations.

G
George Philips
Oct 24, 2026 • 21 Reads

MOTS-c Peptide Buy Guide: What to Check Before You Purchase

Searching for mots-c peptide buy online can lead to websites advertising research-grade materials, high purity percentages, and laboratory-tested products. However, a professional-looking listing does not automatically prove that a substance is authentic, accurately labeled, or safe for a particular use. Before relying on a supplier's claims, it is important to understand the available scientific evidence, examine product documentation, and distinguish marketing language from independently verifiable information.MOTS-c is a mitochondrial-derived peptide investigated for its potential role in cellular metabolism and energy regulation. Researchers have explored its biological activity in laboratory and animal studies, but these findings do not establish that it is safe or effective as a treatment in humans. The amount of reliable clinical evidence remains limited, so claims about metabolic improvement, weight management, or athletic performance should be assessed cautiously.This guide explains how to evaluate supplier documentation, interpret certificates of analysis, recognize common warning signs, and understand the difference between MOTS-c and products marketed as klow peptide. These steps can help readers make better-informed assessments without assuming that online availability, a purity claim, or a research-use label guarantees quality or clinical suitability.What Is MOTS-c and Why Is It Being Studied?MOTS-c is a short peptide associated with mitochondrial biology and cellular energy regulation. Scientific interest has focused on how it may interact with metabolic pathways, including mechanisms related to glucose utilization and cellular responses to metabolic stress. Much of this work remains at the experimental stage, and findings from cells or animals cannot automatically be applied to humans. Understanding this distinction is essential when interpreting claims made by suppliers or third-party websites.Online descriptions sometimes present mots-c peptide buy as a proven solution for weight management, exercise performance, or healthy aging. Such statements can overstate what current research establishes. A biological mechanism that appears promising in an experiment does not necessarily translate into a clinically meaningful benefit, and it does not reveal the full safety profile of a compound. Readers should look for well-designed human studies and reliable regulatory information before accepting claims about potential benefits.It is also important to understand the compound's intended use before assessing a listing. A substance sold as a research material should not automatically be treated as an approved medicine, dietary supplement, or product suitable for personal administration. Researchers should follow institutional requirements and applicable laws, while individuals seeking medical care should consult a qualified healthcare professional. This distinction provides a sound starting point for evaluating any MOTS-c-related information.How to Evaluate a MOTS-c SupplierWhen researching mots-c peptide buy options, begin by examining how clearly a supplier identifies its product and explains its claims. The listing should provide consistent information about the material, its stated form, its intended use, and the documentation available. Vague descriptions, exaggerated health promises, or unclear company information make it more difficult to evaluate credibility. A polished website alone is not evidence that the material meets appropriate quality standards.A supplier's supporting records are more informative than promotional phrases such as “premium grade” or “guaranteed quality.” Look for a certificate of analysis (COA) that identifies the tested material, includes a batch or lot number, names the laboratory, and describes the analytical methods used. The report should provide actual results and enough information to connect them to the product being described. A generic certificate that cannot be matched to a specific batch offers limited assurance.Consider whether the supplier explains the limitations of its testing rather than claiming that one report proves everything. Different analytical methods answer different questions, and no single test necessarily establishes identity, purity, sterility, stability, and safety. If a supplier cannot explain what its documentation covers, it is reasonable to remain uncertain about the strength of its quality claims. Transparency is useful, but it should be supported by verifiable evidence rather than promises alone.Understanding Purity, Testing, and Certificates of AnalysisPurity is a common selling point in online peptide listings, but a percentage should not be interpreted without understanding the analytical method. High-performance liquid chromatography (HPLC) can help assess chromatographic purity by separating components in a sample. Mass spectrometry can provide complementary information about molecular mass and support compound identification. Although these methods can contribute to quality assessment, they do not independently establish every characteristic relevant to a product's intended use.A COA should distinguish between the identity of the material, its reported purity, and the amount of compound present. These measurements are related but not interchangeable. A sample may have a high chromatographic purity result without that figure confirming the exact labeled quantity or ruling out every possible contaminant. Testing results should therefore be reviewed in context, with attention to the methods used and the characteristics that were not assessed.Batch traceability is another important consideration. The lot number on a report should correspond to the product documentation, and the laboratory's identity and role should be clear. Independent testing may strengthen confidence in specific claims when the report is authentic and relevant, but it cannot prove clinical effectiveness. For MOTS-c, as with other experimental peptides, laboratory characterization should not be confused with evidence that the compound is safe for human use.MOTS-c vs. Klow Peptide: Important DifferencesThe term klow peptide is used in commercial listings for products marketed under the KLOW name, but it does not necessarily refer to one standardized formulation. Some products sold under this label are described as blends containing combinations of compounds such as GHK-Cu, BPC-157, TB-500, or KPV. Formulations may vary between sellers, so the name alone cannot establish the ingredients, quantities, or quality of a particular product. The actual composition must be assessed from product-specific information.MOTS-c and KLOW-labeled products should not be treated as interchangeable. MOTS-c is investigated in connection with mitochondrial biology and metabolic pathways, whereas a blend may contain multiple compounds with different proposed biological activities. Evidence about MOTS-c does not establish the properties of a KLOW formulation, and research on an individual ingredient does not prove that a combination is safe or effective. Each substance or formulation requires its own evidence assessment.Quality testing for a blend can also be more complex than testing a single compound. A COA that reports results for one ingredient does not validate every component in a multi-ingredient formulation. Researchers evaluating such materials should determine whether the documentation applies to the complete product and whether the methods support the claims being made. Marketing a blend under a recognizable name is not a substitute for transparent composition details and appropriate testing.Red Flags to Watch for Before Trusting a ListingOne major warning sign is a supplier that guarantees medical outcomes without credible supporting evidence. Claims that MOTS-c will reliably improve metabolism, cause weight loss, increase endurance, or reverse aging should not be accepted simply because they appear on a product page. Testimonials and personal stories may reflect individual experiences, but they cannot establish effectiveness or identify potential long-term risks. Reliable conclusions require appropriate scientific studies and careful interpretation.Other concerns include missing batch identifiers, laboratory reports that do not match the product name, and vague descriptions of testing procedures. Be cautious when a seller advertises exceptionally high purity but provides no meaningful supporting documentation. A high price does not guarantee better quality, and a low price does not independently prove that a product is counterfeit. The important question is whether the seller's claims can be verified through consistent and relevant evidence.A “research use only” statement should also be understood correctly. It does not certify the material's purity, demonstrate that it is safe, or authorize personal use. In the United States, the FDA has raised concerns about limited safety information and potential risks involving compounded MOTS-c, including issues related to immunogenicity and peptide impurities. Regulatory requirements differ by jurisdiction, so readers should consult current official guidance instead of relying on a supplier's interpretation.Safety, Storage, and Responsible ResearchMOTS-c remains an experimental peptide, and the available evidence is not sufficient to establish a comprehensive human safety profile. Laboratory findings may help researchers understand biological mechanisms, but they do not determine safe doses, appropriate administration methods, or possible interactions for people. Anyone considering a compound for a health concern should seek advice from a qualified healthcare professional rather than relying on online vendors or self-directed experimentation.Storage requirements depend on the compound, formulation, and supplied form. Factors such as temperature, moisture, and light may affect stability, but general advice for one peptide should not automatically be applied to another. Researchers should follow verified product-specific documentation and appropriate laboratory procedures. Claims that a product remains stable indefinitely or retains all its stated properties under any conditions should be treated cautiously unless supported by relevant data.Responsible research also involves following institutional requirements, applicable laws, and suitable handling procedures. Product identity and purity are only parts of a broader quality assessment, and neither proves that a substance is appropriate for personal administration. Where a product's composition, documentation, or intended use is unclear, uncertainty should be acknowledged rather than filled with assumptions. This approach helps keep scientific evaluation separate from promotional claims.Final Checklist for Evaluating MOTS-c Peptide ListingsBefore trusting a MOTS-c listing, check that the product is clearly identified, the available COA matches the relevant batch, and the laboratory methods are explained. Review whether the supplier distinguishes identity testing from purity testing and avoids claiming that laboratory results prove clinical effectiveness. Also examine whether the product description is consistent with its supporting records and whether the supplier acknowledges the limitations of the available evidence.When comparing mots-c peptide buy information, prioritize traceable documentation and credible scientific sources over testimonials, dramatic promises, or phrases such as “verified quality.” Apply the same care to klow peptide listings, especially when the product is a blend whose composition may differ between suppliers. A report for one compound cannot validate another, and a test of an individual ingredient cannot establish the quality of an entire formulation.Ultimately, an informed assessment begins with understanding what is known, what remains uncertain, and what a supplier's evidence can genuinely establish. MOTS-c research may contribute to scientific understanding of cellular metabolism, but promising experimental findings do not prove that a commercial product is safe or effective for people. By checking documentation, recognizing unsupported claims, and consulting appropriate scientific and regulatory sources, readers can evaluate peptide-related information more responsibly.

J
Josan Brown
Oct 23, 2026 • 22 Reads

Apply for Instant Personal Loan Online | Up to ₹5 Lakh

What Is an Instant Personal Loan?An unexpected hospital bill, a sudden home repair, a wedding expense, or a gap between salary credits can throw even a carefully planned month off balance. This is where an instant personal loan becomes useful. It is an unsecured loan, which means you don't have to pledge property, gold, or any other asset as collateral, and the money is sanctioned and disbursed quickly once your application and documents are verified.Online personal loan platforms have made the entire process faster and more accessible than visiting a bank branch. A salaried individual with a steady income can now apply for a personal loan of up to ₹5 lakh from a phone or laptop, upload a few documents, and receive a lending decision within minutes to a few hours, depending on the lender's verification process.This guide walks you through how an instant personal loan works, who is eligible, what documents are needed, how interest rates and fees are usually structured, and what you should check before signing up — so that you can borrow responsibly and avoid surprises later.What Does 'Up to ₹5 Lakh' Actually Mean?When a lender advertises loans 'up to ₹5 lakh', it means ₹5 lakh is the upper limit of what some applicants may qualify for — not a fixed amount every borrower receives. The actual sanctioned amount depends on several factors: your monthly income, existing loan obligations, credit history, employment stability, and the lender's own internal risk assessment.A first-time borrower or someone with a modest salary may be offered a smaller amount, often in the range of ₹10,000 to ₹1 lakh, while borrowers with a strong, verifiable income and a healthy credit score may be considered for amounts closer to the ₹5 lakh ceiling. It's important to apply for an amount that matches your actual need and your ability to repay comfortably, rather than the maximum the lender shows you.Who Can Apply? Eligibility Criteria ExplainedEligibility requirements vary slightly between lenders, but most instant personal loan providers in India look at a similar set of basic criteria:•     Age: Typically between 21 and 58 years at the time of application.•     Nationality and residency: Indian citizen with a permanent or current residential address in India.•     Employment type: Salaried employees of private companies, public sector units, MNCs, or government bodies; some lenders also cater to self-employed individuals and professionals.•     Minimum income: Often a monthly net income of ₹15,000–₹25,000, though this threshold differs by lender and city.•     Credit history: A credit score (usually CIBIL) is checked by most regulated lenders. A score of 700 or above generally improves approval chances and the interest rate offered, though some platforms also consider applicants with limited or lower credit history on a case-by-case basis.•     Banking relationship: An active savings or salary bank account where the loan can be disbursed and EMIs can be auto-debited.Meeting these criteria does not guarantee approval — it means you are eligible to apply. The final decision always rests with the lender after reviewing your complete profile.Documents You Will Typically NeedOne of the biggest advantages of applying online is that most document submission happens digitally — through uploads or e-verification — instead of physical paperwork. Commonly requested documents include:•     Identity proof: Aadhaar card, PAN card, Voter ID, or Passport.•     Address proof: Aadhaar card, utility bill, rental agreement, or passport.•     Income proof: Last 3 months' salary slips for salaried applicants, or the latest income tax returns and bank statements for self-employed applicants.•     Bank statements: Usually the last 3 to 6 months, to verify income flow and existing obligations.•     A recent photograph and a valid PAN card for KYC (Know Your Customer) compliance, as mandated by RBI guidelines.Keeping clear, legible scans or photos of these documents ready before you start the application can significantly reduce processing time.Step-by-Step: How to Apply for an Instant Personal Loan Online1.     Check your eligibilityMost lending platforms offer a quick eligibility checker where you enter basic details like age, income, and employment type to see an estimated loan amount before you formally apply.2.     Fill in the online applicationProvide your personal details, employment information, income details, and the loan amount and tenure you are seeking.3.     Upload the required documentsSubmit identity proof, address proof, income proof, and bank statements through the platform's secure upload feature.4.     Complete KYC verificationThis may be done through Aadhaar-based e-KYC, video KYC, or document verification, depending on the lender's process.5.     Receive the loan offerIf your application is approved, the lender will share the sanctioned amount, interest rate, tenure, processing fee, and EMI schedule for your review.6.     Accept the terms and sign digitallyRead the loan agreement carefully, including all charges, before accepting it through an e-sign or OTP-based authorization.7.     DisbursalOnce everything is verified and accepted, the loan amount is credited directly to your registered bank account — often within a few hours for straightforward cases, though timelines can vary.Interest Rates, Processing Fees, and Other ChargesPersonal loan interest rates are typically offered on a reducing balance basis and can vary widely — commonly somewhere between 10% and 36% per annum — depending on your credit profile, income stability, loan amount, tenure, and the specific lender's policies. Borrowers with a strong credit score and stable income history are usually offered rates at the lower end of this range.Beyond the interest rate, it's important to understand the full cost of borrowing. Common charges include:•     Processing fee: A one-time fee, often a percentage of the loan amount, deducted at disbursal or added to the loan.•     Prepayment or foreclosure charges: Some lenders charge a fee if you repay the loan earlier than the agreed tenure, though RBI guidelines have reduced such charges for many floating-rate loans to individual borrowers.•     Late payment penalty: Charged if an EMI is missed or delayed beyond the due date.•     GST: Applicable on processing fees and certain other charges as per prevailing tax rules.Always ask for the Annual Percentage Rate (APR) or the total cost of the loan — this single figure combines interest and fees and makes it much easier to compare offers from different lenders on a like-for-like basis.How Lenders Decide Your Loan Amount and Interest RateLenders generally use a combination of factors to arrive at the amount they are willing to offer and the rate they will charge:•     Fixed Obligation to Income Ratio (FOIR): This measures how much of your monthly income already goes toward existing EMIs and fixed obligations. A lower FOIR generally improves your eligibility for a higher loan amount.•     Credit score and repayment history: A consistent track record of on-time repayments on past loans or credit cards signals lower risk to the lender.•     Employer and income stability: Working with a well-established employer or having a longer, more stable income history can work in your favour.•     Existing relationship with the lender: Some lenders offer pre-approved or preferential terms to customers who already bank with them or have repaid a loan with them before.Benefits of Applying for a Personal Loan OnlineChoosing a digital application process over a traditional branch visit offers several practical advantages:•     Speed: Eligibility checks, document uploads, and verification can often be completed within the same day, compared to the longer timelines typical of branch-based processing.•     Convenience: You can apply from home or work, at any time, without taking time off to visit a branch.•     Minimal paperwork: Digital KYC and e-signatures reduce the need for physical documents.•     Transparency: Most platforms clearly display the interest rate, fees, and EMI amount before you accept the offer, making it easier to compare and decide.•     No collateral required: Since personal loans are unsecured, you don't need to pledge property, gold, or investments.Things to Check Before You ApplyBefore submitting an application, it's worth spending a few minutes reviewing these points carefully: •     Confirm the lender is a registered NBFC, bank, or operates in partnership with one — this is usually mentioned in the platform's 'About Us' or legal/disclosure pages.•     Read the full fee structure, not just the headline interest rate — processing fees, late fees, and foreclosure charges all affect the real cost of the loan.•     Use an EMI calculator to check whether the monthly instalment comfortably fits your budget alongside your other expenses and obligations.•     Check your own credit report beforehand, if possible, so you know roughly where you stand and aren't surprised by the terms offered.•     Borrow only what you need. A larger sanctioned amount is not an invitation to take the maximum — it increases your EMI and total interest outgo.Common Mistakes to Avoid•     Applying to multiple lenders at the same time: Each hard credit enquiry can temporarily lower your credit score, and repeated enquiries in a short span may make lenders view you as credit-hungry.•     Ignoring the fine print: Skipping the loan agreement and only looking at the EMI amount can mean missing important details about fees or penalty clauses.•     Borrowing beyond repayment capacity: Taking the maximum amount offered, rather than what you actually need, can strain your monthly budget.•     Not checking the lender's authenticity: Only apply through lenders or platforms that clearly disclose their registration details and contact information.•     Missing EMI due dates: Late payments can attract penalty charges and negatively affect your credit score, making future borrowing more expensive.Repayment: Understanding Your EMIA personal loan is repaid through Equated Monthly Instalments (EMIs) over a chosen tenure, which typically ranges from a few months up to 5 years, depending on the lender and loan amount. Each EMI consists of a principal component and an interest component; in the early months of the tenure, a larger share of the EMI typically goes toward interest, gradually shifting toward principal as the loan matures.Most lenders set up an auto-debit mandate (NACH/ECS) from your bank account on a fixed date each month, so it's important to ensure sufficient balance is available on the due date to avoid bounce charges or late fees. If you anticipate a shortfall, contacting the lender proactively is usually a better option than letting an EMI fail.An instant personal loan of up to ₹5 lakh can be a practical way to manage a genuine financial need — whether it's a medical emergency, a planned expense, or consolidating existing debt — provided it's approached with the same care as any other financial decision. Understanding your eligibility, comparing the real cost of borrowing across lenders, reading the loan agreement carefully, and borrowing only what fits comfortably within your repayment capacity are the habits that make online lending work in your favour rather than against it.Take a few minutes to check your eligibility, compare offers, and read the terms before you apply — a well-informed decision today can save you both money and stress down the line.Frequently Asked Questions (FAQ)How quickly can I get an instant personal loan online?Processing times vary by lender, but many digital lending platforms complete eligibility checks and document verification within a few hours of a complete application, with disbursal following shortly after approval. Complex cases or additional verification can take longer.Do I need collateral to get a personal loan up to ₹5 lakh?No. Personal loans are unsecured, which means you do not need to pledge property, gold, or any other asset. Approval is based mainly on your income, credit profile, and repayment capacity.Will applying for a personal loan affect my credit score?A formal loan application usually triggers a hard enquiry on your credit report, which can cause a small, temporary dip in your score. Multiple applications within a short period can have a larger effect, so it's advisable to check your eligibility first and apply selectively.Can I get a personal loan with a lower credit score?Some lenders do consider applicants with a limited or lower credit score, but this may come with a smaller sanctioned amount, a higher interest rate, or additional documentation requirements, depending on the lender's policy.What is the maximum tenure for repaying a personal loan?Tenure options typically range from a few months up to 5 years, though the exact range depends on the lender and the loan amount. A longer tenure reduces the EMI but increases the total interest paid over the life of the loan.Can I prepay or foreclose my personal loan early?Most lenders allow prepayment or foreclosure after a minimum lock-in period, though some charge a fee for doing so. It's worth checking the specific prepayment terms in your loan agreement before signing.Is it safe to apply for a personal loan online?Applying online is generally safe when you use a legitimate, registered lender or a platform that clearly discloses its registration and contact details, and uses secure, encrypted channels for document upload and KYC verification.

I
Insta Loans
Oct 19, 2026 • 35 Reads

Dumpster Rental Denver: A Complete Guide to Sizes, Costs, and Services

IntroductionHome renovations, construction projects, property cleanouts, and commercial operations can generate substantial amounts of waste. Managing that waste efficiently requires a practical disposal solution that accommodates the project's size, schedule, and material requirements.A dumpster rental in Denver provides a convenient way to collect and remove unwanted materials without making repeated trips to a disposal facility. Homeowners, contractors, landlords, and business owners can select containers based on their waste volume and arrange delivery and pickup according to their project timelines.Denver's mix of residential neighborhoods, commercial properties, and ongoing renovation projects creates demand for different dumpster rental Denver options. Understanding container sizes, pricing factors, delivery requirements, and local disposal rules helps customers choose an appropriate service.What Is Dumpster Rental?Dumpster rental is a waste management service in which a provider delivers a container to an approved location, allows the customer to fill it during an agreed rental period, and collects it for disposal or processing.Roll-off dumpsters are particularly useful for temporary projects that generate large amounts of debris. Smaller containers and recurring waste collection services may be more appropriate for routine residential or commercial waste.The best dumpster rental depends on the type of waste, the amount generated, the available placement area, and the required collection schedule.Common Types of Dumpster Rental ServicesResidential dumpster rental: Suitable for garage cleanouts, moving, home renovations, landscaping projects, and decluttering.Construction dumpster rental: Designed for approved building materials, demolition debris, roofing waste, and renovation projects.Commercial dumpster rental: Supports businesses that generate regular waste, including retail stores, offices, restaurants, and warehouses.Yard waste dumpster rental: May accommodate approved branches, leaves, and other landscaping materials, depending on the provider's restrictions.Roll-off dumpster rental: Uses an open-top container delivered by a specialized truck and is commonly used for temporary projects that generate substantial waste.Customers should confirm the accepted materials and service terms before choosing a container.Dumpster Rental Sizes in Denver, COSelecting the right dumpster size can help prevent unnecessary expenses and reduce the risk of running out of space during a project.Dumpster capacity is commonly measured in cubic yards. The appropriate size depends on the volume and weight of the materials being discarded.Common Dumpster Sizes and Their UsesDumpster size Typical applications10-yard Small cleanouts, minor renovations, and limited debris 15-yard Medium-sized cleanouts and smaller remodeling projects 20-yard Flooring removal, larger household cleanouts, and moderate renovations 30-yard Major renovations, substantial construction debris, and large property cleanouts 40-yardLarge construction projects and extensive demolition or cleanup workThese sizes are general guidelines. Actual container dimensions, weight limits, and availability vary by rental provider.How to Choose the Right Dumpster SizeSeveral factors influence the ideal container size.Project scope: A small bathroom renovation generally produces less debris than a full-home remodel.Waste weight: Concrete, brick, soil, and roofing materials can reach weight limits quickly.Available space: The property must accommodate the dumpster and provide safe access for delivery and collection trucks.Rental duration: Larger projects may require additional days or multiple container exchanges.Material restrictions: Certain waste types may require specialized containers or separate disposal arrangements.When the required capacity is uncertain, customers should describe the project and estimated debris volume to the rental provider before booking.How Much Does Dumpster Rental Cost in Denver?The cost of dumpster rental in Denver varies according to container size, rental duration, included weight, disposal fees, and the type of material being discarded.Some providers offer flat-rate packages, while others apply additional charges for excess weight, extended rental periods, or extra collections.A reliable price comparison should account for the complete rental cost rather than just the advertised starting rate.Factors That Affect Dumpster Rental PricesPricing factor Potential cost impact Dumpster size Larger containers may have higher rental rates Rental period Additional days may incur extension charges Weight allowance Exceeding the included limit may trigger overage fees Delivery and pickup Charges may be included or billed separately Disposal fees Different materials can have different processing costs Additional collections Extra pickups or exchanges may increase the total Placement permits Public-property placement may involve separate feesHow to Get an Accurate Rental QuoteCustomers should request an itemized quote that explains the rental period, included weight, delivery, pickup, disposal charges, and possible additional fees.Comparing quotes for equivalent container sizes and rental terms makes it easier to identify the most suitable option.To control costs, customers can estimate the debris volume, separate recyclable materials where appropriate, and avoid placing prohibited items in the dumpster. Heavy materials should be discussed with the provider before delivery.When Should Customers Rent a Dumpster in Denver?Dumpster rental can support many residential, commercial, and construction projects throughout Denver.Home Renovations and RemodelingKitchen upgrades, bathroom renovations, flooring replacement, and interior remodeling can generate large quantities of discarded materials.A roll-off dumpster provides a central location for collecting approved debris and helps keep the work area organized throughout the project.Garage and Property CleanoutsGarages, basements, attics, and storage areas often contain unwanted furniture, broken household items, and accumulated clutter.A residential dumpster can simplify these cleanouts by allowing approved materials to be collected in one container instead of being transported in multiple trips.Roofing and Construction ProjectsRoof replacements, demolition work, and building renovations can produce bulky or heavy debris.Customers should verify whether roofing shingles, wood, drywall, concrete, and other construction materials are accepted. Weight limits are especially important for dense materials.Commercial Waste ManagementBusinesses may require temporary dumpsters during relocations, remodeling, inventory cleanouts, or property improvements.For ongoing waste collection, a recurring commercial service may be more suitable than a temporary roll-off rental. The choice depends on the business's waste volume and collection requirements.Landscaping and Yard CleanupLandscaping projects can produce branches, leaves, soil, rocks, and other outdoor debris.Not every provider accepts all yard materials in a standard dumpster. Customers should confirm material restrictions and weight limits before selecting a container.How to Find Reliable Dumpster Rental in DenverChoosing a provider involves more than comparing prices. Service availability, delivery reliability, accepted materials, and rental conditions all influence the overall experience.1. Confirm Service AvailabilityCheck whether the provider serves the exact project address in Denver or the surrounding area. Delivery availability and scheduling can vary by neighborhood and demand.2. Compare Container OptionsReview the available sizes, container dimensions, weight allowances, and recommended applications. A suitable container should accommodate the expected waste without exceeding its permitted capacity.3. Request a Detailed QuoteAsk whether the quoted rate includes delivery, pickup, disposal, and the full rental period. Clarify charges for extra days, additional pickups, and excess weight.4. Review Customer FeedbackLook for consistent feedback about on-time delivery, transparent pricing, container condition, and collection reliability.5. Check Rental TermsUnderstand the cancellation policy, prohibited materials, extension charges, and process for arranging pickup before agreeing to the rental.6. Verify Placement RequirementsDetermine whether the dumpster can be placed on private property or requires a public-property permit. Confirm the delivery area can accommodate the truck and container safely.These steps help customers compare services based on value, suitability, and reliability rather than price alone.Dumpster Placement and Permit Requirements in DenverDumpster placement is an important consideration for projects in Denver, particularly when a container must occupy a street, sidewalk, or other public area.Private Property PlacementA driveway, private parking area, or designated work zone may provide a convenient location for a dumpster. However, the surface must be able to support the container and its contents.Customers should confirm clearance requirements and ask whether protective boards or other surface protection are recommended.Street and Public Right-of-Way PlacementPlacing a dumpster on public property may require authorization from the relevant local authority. Requirements can depend on the exact location, duration, and type of obstruction.Customers should verify current City and County of Denver requirements before arranging street placement. They should also confirm whether the rental provider assists with permits or whether the customer must arrange them independently.Checking placement rules before delivery can help prevent delays, fines, and unexpected expenses.What Can and Cannot Go Into a Rental Dumpster?Accepted materials depend on the provider, disposal facility, and applicable regulations.Commonly Accepted MaterialsDepending on the rental agreement, dumpsters may accept:Household clutter and unwanted furniture.Wood and approved renovation debris.Drywall and flooring materials.Cardboard and packaging.Approved roofing materials.Certain landscaping debris.Restricted or Prohibited MaterialsSome items require separate disposal arrangements or are prohibited in standard rental containers.Examples include hazardous chemicals, fuels, solvents, certain batteries, asbestos, and some electronic waste. Appliances containing refrigerants may also require specialized handling.Concrete, bricks, and soil may have specific weight or container restrictions.Customers should obtain an accepted-material list before loading the dumpster. This helps prevent rejected waste, additional fees, and potential safety or environmental issues.Tips for a Successful Dumpster RentalA few practical preparations can help keep a Denver dumpster rental organized and efficient.Estimate the waste volume: Assess the materials expected from the project before selecting a size.Prepare the placement area: Remove vehicles and obstacles before the scheduled delivery.Protect the surface: Follow the provider's recommendations for driveway or pavement protection.Load materials safely: Distribute waste evenly and keep the contents below the permitted fill line.Monitor weight limits: Heavy debris can exceed the allowance even when the container is not full.Separate restricted materials: Arrange appropriate disposal for items that cannot enter the dumpster.Schedule collection in advance: Confirm the pickup procedure and any notice requirements when booking.These measures can help reduce additional charges and avoid unnecessary project delays.Frequently Asked QuestionsHow much does dumpster rental cost in Denver?Pricing varies by dumpster size, rental period, weight allowance, disposal charges, and service provider. Requesting itemized quotes helps customers compare the total cost of equivalent rental packages.What dumpster size is best for a home renovation?A 10-yard dumpster may suit a small renovation, while a 20-yard or larger container may be more appropriate for extensive remodeling. The final choice depends on the volume and weight of the debris.Can a dumpster be placed on a Denver street?Street placement may require authorization or a permit, depending on the location and circumstances. Customers should verify current local requirements before delivery.How long can a dumpster be rented?Rental periods vary by provider and agreement. Customers should confirm the included number of days and any charges for extending the rental.Can construction debris go into a rental dumpster?Many providers accept approved construction debris, but materials such as concrete, soil, hazardous waste, and certain roofing products may have special restrictions. The provider should confirm acceptance before loading.Is dumpster rental available outside Denver?Some providers serve surrounding communities, but service areas differ. Customers should verify availability for the exact property address rather than assuming nearby cities are covered.ConclusionFinding the right dumpster rental in Denver starts with understanding the project's waste disposal needs, selecting an appropriate container size, and comparing complete rental costs.Customers should also review weight allowances, accepted materials, delivery arrangements, and local placement requirements before booking. Careful planning can help homeowners, contractors, and businesses manage waste more efficiently while avoiding unnecessary charges.The best dumpster rental service combines suitable container capacity, transparent pricing, dependable delivery and pickup, and clear disposal requirements. By comparing these factors, customers can select a practical waste management solution for their Denver project.

5
5280 Waste Solutions
Oct 16, 2026 • 49 Reads

Black Friday Finance Planning: How Can Online Sellers Manage a Sales Surge?

Black Friday means the greatest sales of the year. Your business must be prepared to handle the goods and services well. You may need more stock, and it is high time to upgrade that. Not only that, you must plan the marketing, VAT and other expenses before the day arrives. The goal is not only to sell more. It is about ensuring more profit after paying the liabilities.Why do Black Friday sales strain sellers? A Black Friday order often arrives with high advertising costs, extra packaging, staffing, supplier payments, refunds, and VAT availability. All these things may consume the available cash. Therefore, you may have less flexibility in planning. Here are some risks that businesses may face while planning for Black Friday sales:Running out of best-selling stocks after promoting them heavilyOver-orders and slow-moving products, tying up cashHeavy discounts reduce the profit percentage.Missing the supplier, VAT, payroll, advertising, and other important bill payment datesInability to dispatch orders quickly. It may eventually lead to high cancellations and refund requests.Therefore, there is so much to prepare for and look after as the sales begin. And you may not always be cash-ready. What if you need to re-load inventory and you are out of cash?Here, you may check short-term ecommerce finance for Black Friday sales online. You may use it to re-load inventory as you get the approval the same day. It requires limited documentation and assessment, as it is for quick turnarounds. It helps you fix any small cash gap that you may encounter during Black Friday sales. How to manage the high sales count during Black Friday sales?Here are some ways that might help you manage your sales count during Black Friday sales:Create a sales forecastUnderstanding how much you can earn during Black Friday sales helps you plan the events and finance things accordingly. You can even use the prediction to develop the budget for Black Friday sales.Build 3 forecasts: conservative, realistic, and optimistic for each key product or SKU. You can also use the previous year’s data. Accordingly, adjust the pricing strategy, stock levels, marketing, and marketing conditions.Do not use the supplier’s price only. Instead, create the final price by including VAT, freight costs, customs duties, etc.Protect a 13-day cash flowYou must have a thorough cash flow plan for a 13-day sales period. A customer may pay today; however, marketplace payouts, card settlements, supplier invoices, and VAT payments may come anytime.  To counter that, you can create a 13-day cash flow forecast with weekly inflows and outflows. Here is what to include:Expected sales and payment-settlement dates.Supplier deposits and final stock payments.Import duty, freight, and storage charges.Paid advertising spend and daily spending caps.Packaging, temporary staff, overtime, and fulfilment costs.Refunds, chargebacks, and returns-related costs.VAT, Corporation Tax, payroll, rent, and loan repayments.Keep monitoring the metrics and adjust the budget accordingly. For example, if the freight and storage charges increase, given the competition, extend the budget accordingly. Also, delay non-essential purchases for some time.Plan the stock according to SKUAnalysing and keeping the top-selling products on the upper and visible shelf is the most important. Similarly, you must analyse the available stock and decide the placements according to popularity.You can do the same if you run an online business. Show the most-selling or the best-selling products in each category to capture the buyer’s attention.  You can even discount these products slightly to maximise your sales.Here are some tips that might help:Keep a buffer for the top sellers.Use prior peak season sales, planned promotions, and marketing for forecasting.Analyse the supplier lead times by analysing each aspect. Check manufacturing, shipping, customs, receiving, and listing time.Prepare and label the stock well before putting it on the shelves and running marketing campaigns. Keep an account of each product under each category.Set low stock alerts to re-fill immediately. Otherwise, non-availability of the respective product may affect sales.Monitor the stock daily by the end of the day. It will help you know which items you need to re-stock, given demand and price.If you don’t want to worry about going cashless every time and wish to ensure a consistent stock of the best-selling items, check merchant cash advance for seasonal sales online. This facility helps you cover most of the sales expenses using business credit cards. It is a revolving credit facility where you don’t need to worry about money availability. Instead, you can use it up to the available limit and repay according to the percentage of the sales.Bottom line These are some aspects that may help online sellers manage the Black Friday sales surges. Analyse and forecast expected sales according to previous records and available stock.Decide the budget for each category item and maintain the stock. Analyse the credit facilities to bridge urgent requirements or payrolls. It may help you bridge the requirements without worry.

r
rosiejoe81
Oct 15, 2026 • 36 Reads

Personal Loan for New Employees in Kolkata: Eligibility, Process & Tips

Starting a new job is exciting, but it often comes with fresh expenses too — setting up a new home near your office, buying work essentials, covering a security deposit, or simply managing the gap before your first full salary cycle begins. If you have recently joined a company in Kolkata and need funds quickly, you may be wondering whether a personal loan is even an option for someone with little or no job history. The good news is that it usually is, and this guide explains exactly how it works.Many new employees assume that lenders only approve loans for people with years of work experience. While a longer employment history does help, it is not the only factor lenders consider. Digital lending platforms such as Insta-Loans have adapted their eligibility models to accommodate salaried professionals at every stage of their career, including those in their first few months on the job.Why New Employees in Kolkata Look for Personal LoansRelocating to Kolkata for a new role, or simply starting your first job, brings a set of one-time and recurring costs that your starting salary may not fully cover right away. Some common reasons new employees apply for a personal loan include:•    Paying a rental deposit and advance rent for a new home closer to the workplace•    Buying furniture, appliances, or a two-wheeler for the daily commute•    Covering relocation costs such as transport, packing, and temporary accommodation•    Managing day-to-day expenses during the gap before the first salary credit•    Clearing a small existing debt, such as a family loan or a leftover education expense•    Building an emergency buffer for unexpected medical or family expensesBecause these needs tend to arrive all at once in the first few weeks of a job, many new employees prefer a personal loan over borrowing informally from friends or family, since it is faster, more private, and comes with a clear repayment schedule.Can a New Employee Actually Get a Personal Loan in Kolkata?Yes, in most cases. Lenders assess a loan application on several factors together, not on work experience alone. For a new employee, the most important of these factors are usually:•    Monthly in-hand salary and whether it is credited through a bank account•    The reputation and stability of the employer•    Whether the job role is permanent, contractual, or still on probation•    Existing financial obligations, such as other EMIs or credit card dues•    Credit score and credit history, if any•    Bank statement patterns, including salary credit consistencyBecause digital lenders rely on data-driven underwriting, they are often able to look beyond a short job tenure and approve applicants who show a stable income and a reasonable ability to repay. This is different from some traditional banks, which may set a fixed minimum tenure requirement before they will even consider an application.Typical Eligibility Criteria for New EmployeesWhile exact criteria differ between lenders, the table below gives a general idea of what is commonly expected from a new employee applying for a personal loan in Kolkata. Criteria Typical Requirement Age 21 to 58 years at the time of application Employment type Salaried, working with a private company, government body, or a reputed start-up Minimum tenure in current job As low as the first salary credit with some digital lenders; 6 months preferred by many banks Monthly income Varies by lender; higher income generally improves eligible loan amount Salary account A bank account where salary is credited is usually required Credit score A healthy score helps, but a thin or new credit file is often still considered Residence Should be a resident of India with a valid address in or near Kolkata Documents RequiredNew employees should keep the following documents ready before starting their application:•    PAN card (mandatory for identity and tax verification)•    Aadhaar card or another valid government-issued address proof•    Latest salary slip, or the offer/appointment letter if a salary slip is not yet available•    Bank statements for the last 3 to 6 months showing salary credits where applicable•    A recent passport-size photograph•    Employee ID or any official communication confirming your current employer, if requestedIf you have very recently joined and do not yet have a salary slip, many lenders will accept your offer letter together with proof of the first salary credit in your bank account, so it is worth checking this option with the lender directly.How Lenders Evaluate New Employees DifferentlyBecause a new employee has limited income history with the current employer, lenders typically widen the factors they look at to form a complete picture of repayment ability. This can include:•    Reviewing your previous employment and salary history, if you have switched jobs•    Checking whether your new role is a confirmed position or on a probationary period•    Looking at your bank statement for savings patterns and existing financial discipline•    Considering the sector and reputation of your current employer•    Assessing any co-applicant or guarantor, if the loan amount requested is on the higher sideThis broader evaluation means that a strong application from a new employee can still be approved quickly, even without a long work history, as long as the overall financial picture looks stable.Step-by-Step: How to Apply for a Personal Loan Online in KolkataStep 1: Check your eligibilityUse an online eligibility checker or calculator to get an idea of the loan amount you may qualify for, based on your salary and expenses.Step 2: Fill the online application formVisit insta-loans.com and complete the simple application form with your personal, employment, and income details.Step 3: Upload your documentsUpload your PAN, Aadhaar, salary slip or offer letter, and recent bank statements directly through the website or app.Step 4: VerificationThe lender verifies your identity, employment, and income details. This step is usually completed quickly for digital applications with complete documentation.Step 5: Approval and e-signingOnce approved, you will receive the loan offer with the amount, interest rate, and tenure. Review the terms and e-sign the agreement online.Step 6: DisbursalThe approved loan amount is transferred directly to your bank account, often on the same day as approval.Tips to Improve Your Approval Chances as a New Employee•    Apply for an amount that comfortably fits your current salary rather than the maximum you may be offered•    Keep your bank statements clean, with salary credits clearly visible and minimal bounced payments•    Avoid applying to multiple lenders at the same time, as repeated credit checks can affect your score•    If you have any existing EMIs or credit card dues, try to keep them well within your repayment capacity•    Provide complete and accurate documents the first time to avoid delays in verification•    Consider a shorter tenure if you can manage a slightly higher EMI, as it can sometimes support a better rate•    If your credit history is thin, highlight stable factors like your employer's reputation and consistent incomeInterest Rates and Loan Amounts for New EmployeesInterest rates for new employees are generally in line with standard personal loan rates, though applicants with limited credit history or a very short job tenure may occasionally be offered a slightly higher rate or a lower initial loan amount compared to someone with an established income history. As you build a track record with your employer and maintain timely repayments, you typically become eligible for larger amounts and better terms on future loans. It helps to think of your first personal loan as a step that also builds your credit profile for the future.Common Mistakes New Employees Should Avoid•    Borrowing more than needed simply because a higher amount is offered•    Not reading the loan agreement carefully before e-signing, especially charges and the repayment schedule•    Missing the first few EMIs due to not planning around the salary credit date•    Ignoring processing fees and other charges while comparing loan offers•    Applying without first checking basic eligibility, which can lead to avoidable rejectionsWhy Consider Insta-LoansInsta-Loans is built for exactly these situations, where a new employee needs a quick, transparent, and fully online personal loan without unnecessary paperwork. The platform is designed to evaluate applications based on your actual income and repayment ability, rather than relying solely on how long you have been in your current job. With a simple digital process, applicants in Kolkata can check eligibility, apply, and track their application from their phone, with funds disbursed quickly once approved.Being new to a job does not have to stand in the way of getting financial support when you need it. With the right documents, a clear understanding of what lenders look for, and a realistic loan amount in mind, new employees in Kolkata have a genuine chance of approval, especially through digital lenders that take a broader view of eligibility. If you have recently started a new role and need funds for settling in, it is worth checking your eligibility and exploring your options before committing to any other, more expensive form of borrowing.Frequently Asked QuestionsCan a new employee get a personal loan in Kolkata?Yes. Many lenders, including digital lenders like Insta-Loans, consider applications from employees who have recently joined a company, especially if the employer is well established and the salary is credited through a bank account. Some lenders ask for a minimum of 1 to 3 months of employment, while others may accept the latest offer letter and salary slip even within the first month.What is the minimum work experience required for a personal loan?Requirements vary by lender. Traditional banks often prefer at least 6 months in the current job and 1 to 2 years of total work experience. Digital lenders are more flexible and may approve applicants with as little as 1 to 3 months in a new role, particularly for salaried professionals in stable sectors.What documents does a new employee need to apply for a personal loan?You typically need your PAN card, Aadhaar card, latest salary slip or offer letter, bank statements for the last 3 to 6 months, and a passport-size photograph. If you do not yet have a salary slip, an offer letter along with the first salary credit in your bank account can often be used instead.Will a probation period affect my loan approval?It can. Some lenders are cautious about applicants still on probation because confirmation is not guaranteed. However, several digital lenders focus more on your salary amount, bank statement patterns, and credit history than on your probation status, so approval is still possible.How much loan amount can a new employee in Kolkata get?Loan amounts depend on your monthly salary, existing obligations, and the lender's policy, and typically range from a small personal loan amount up to a higher limit for well-qualified applicants. New employees with limited income history are usually offered amounts on the lower end of a lender's range to begin with.Does a low or no credit score stop a new employee from getting a loan?A low or thin credit file can affect the interest rate or approved amount, but it does not automatically disqualify you. Lenders also look at your salary, employer reputation, and repayment capacity. Building a short credit history through timely bill or EMI payments can improve future applications.How long does it take to get a personal loan approved?With online lenders like Insta-Loans, eligible applicants can often receive an approval decision within a few minutes to a few hours after submitting complete documents, with disbursal following soon after, subject to verification.Can I apply for a personal loan online without visiting a branch?Yes. The entire process, from filling the application form to uploading documents and e-signing the agreement, can usually be completed online from your phone or computer, without needing to visit a physical branch.

I
Insta Loans
Oct 14, 2026 • 35 Reads

What Types of Bubble Wrap Are Best for Fragile Items?

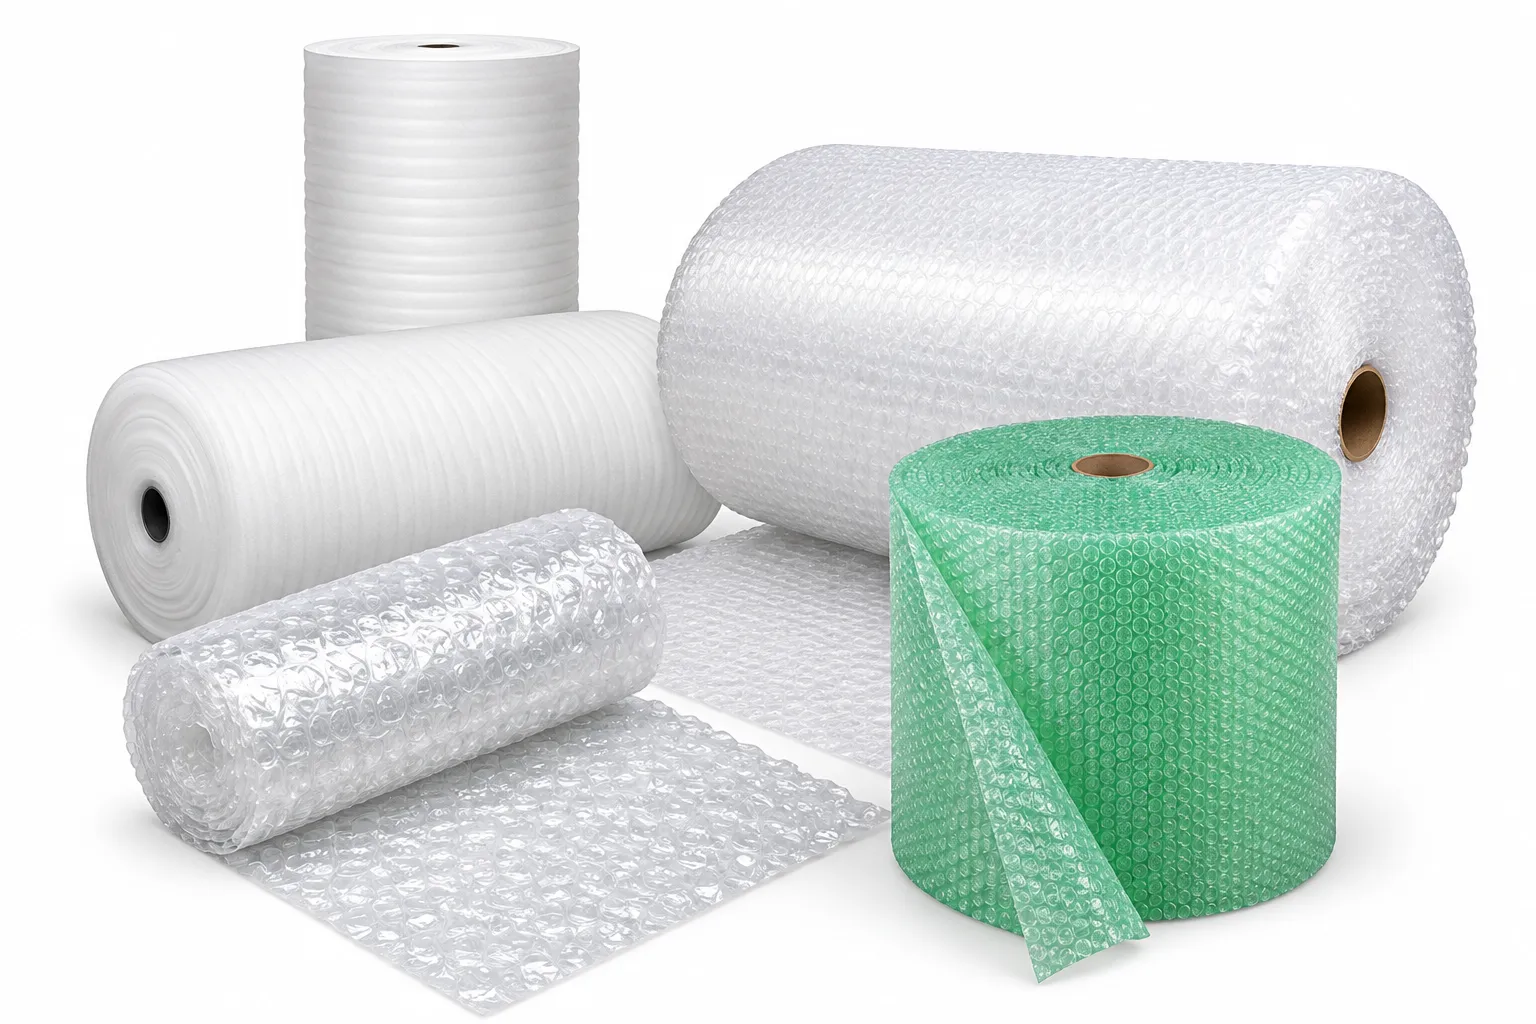
If you’ve ever unwrapped a parcel and heard a worrying rattle, you know how much good padding matters. Glasses, ceramics, gadgets, and gifts all need a little extra care on their journey, and the right cushioning is often the difference between a happy customer and a refund. The trouble is, there are so many rolls, widths, and materials to choose from. In this guide, we’ll walk you through the types buyers look for most, explain what each one does best in plain English, and help you choose for your own delicate goods. Whether you’re sending a single present or a few hundred orders a week, bubble wrap and its alternatives have you covered. TL;DRFine-bubble rolls wrap neatly around small and delicate itemsLarger bubbles suit bulkier, heavier goodsGreen and paper rolls give you an eco-friendly optionFoam rolls protect polished surfaces from scratchesPouches and padded bags suit smaller postal itemsWhy Does the Right Padding Matter for Delicate Items?Fragile goods face knocks, drops, and vibrations on every journey. Good wrapping spreads impact, keeps your item from moving, and protects its surface. Think about a candle seller or a glassware shop: one cracked item means a replacement, a refund, and a disappointed customer. Choosing the right wrap up front costs very little compared with all that, and it speeds up packing, too. The right width means less cutting and less tape, which adds up over a busy week.Which Types Work Best for Fragile Items?Here are the five we’d put on your shortlist. Each one has its own sweet spot.Fine-Bubble RollsThe classic choice for small, delicate things. Small bubble wrap wraps tightly around awkward shapes, and it comes in widths from 300 mm to 1500 mm.Great for glassware, ornaments, and small gadgetsSeven widths to choose fromEasy to fold and tapeLarge-Bubble RollsFor heavier or bulkier items, bigger bubbles provide more cushioning. They fill gaps in larger boxes and keep heavier items in place.Ideal for larger and heavier fragile goodsSame seven widths, from 300 mm to 1500 mmHandy for filling gaps inside boxesGreen and Paper RollsFor a greener option, biodegradable bubble wrap comes in 400 mm, 500 mm, 750 mm, and 1500 mm widths. The film is made from recycled, recyclable LDPE. There’s also a paper version made from recycled paper.Paper rolls available in 500 mm and 750 mm widthsRecyclable options for eco-minded sellersA good fit for gift and homeware brandsFoam RollsFor polished, painted or easily scratched surfaces, foam wrap rolls are a favourite. They’re soft, non-abrasive, water-repellent and leave no residue.Thicknesses from 1 mm to 4 mmWidths of 500 mm, 750 mm and 1500 mmIdeal for glassware, crockery and electronicsBubble Pouches and Padded BagsSmall items often don’t need a full roll. Pouches and padded bags are ready to fill and seal.Pouches in seven sizes, from 100 x 135 mm to 380 x 435 mmPadded bags suit books, accessories and gadgetsQuick to pack for busy sellersHow Do You Match the Wrap to Your Item?Start with what you’re sending, then think about the journey. Here’s a quick guide with a few real-world examples: If you sell gifts or homeware and want to cut down on plastic, try biodegradable bubble wrap on a small batch first. For very delicate items, wrap them in foam wrap rolls first, then add a layer of bubble wrap for extra protection.What Should You Check Before You Order?A little planning saves a lot of headaches. Here’s what we’d look at:The width of the roll against the size of your itemHow many layers you’ll need for your most fragile goodsWhether you’d like a mix of rolls to cover different productsYour box size, so there’s room for padding on every sideOrders placed by 3 PM ship the next working day, so you don’t need to stockpile.Which Wrap Should You Choose?Honestly, there’s no single best option, just the right one for what you’re sending. Fine bubbles suit small items, larger bubbles suit heavier goods, foam protects surfaces, and green rolls keep things eco-friendly. When in doubt, test a few rolls on your own products and see how they hold up. If you’re still unsure, start with a small order of two or three types and see which one your products like best. The right bubble wrap will keep your goods safe and your customers smiling.FAQsWhich bubble size is best for fragile items?Smaller bubbles suit small, delicate things, while bigger bubbles suit heavier goods. For glassware, start with small bubble wrap.Is foam better than bubble rolls?It depends on the item. Foam wrap rolls are great for scratch-prone surfaces, while bubble wrap adds cushioning. Many sellers use both.Are there eco-friendly options?Yes, green and paper rolls are available. Biodegradable rolls come in several widths, and paper rolls come in 500 mm and 750 mm.How many layers should I use?For most fragile items, start with two or three layers. Very delicate goods may need more, plus a snug box.What widths are available?Small and large bubble rolls come in seven widths from 300 mm to 1500 mm. Foam rolls come in 500 mm, 750 mm, and 1500 mm.

M
Mark Dawson
Oct 12, 2026 • 44 Reads

How to Apply for an Instant Personal Loan Online in India

A sudden medical bill, a wedding expense that's crept up faster than planned, a home repair that can't wait, or simply the gap between one salary and the next — these are the moments when an instant personal loan can genuinely help. In India, applying for a personal loan no longer means standing in a bank queue with a folder of photocopies. Today, the entire journey — from checking eligibility to receiving money in your account — can happen on your phone in under an hour.This guide walks you through exactly how the online personal loan process works in India: who qualifies, what documents you need, how the application unfolds step by step, and what to watch out for so you borrow responsibly and don't overpay.What Is an Instant Personal Loan?An instant personal loan is an unsecured loan — meaning you don't have to pledge any collateral like property or gold — that is approved and disbursed quickly, often within minutes to a few hours, through a fully digital application process. Because there's no asset backing the loan, lenders rely on your income, credit history, and repayment behaviour to decide how much to lend you and at what interest rate.These loans are typically used for:●     Medical emergencies●     Travel or wedding expenses●     Home renovation or repairs●     Debt consolidation●     Education costs●     Festival or family expenses●     Bridging a temporary cash-flow gapLoan amounts usually range from a few thousand rupees to several lakhs, with repayment tenures stretching from a few months to five years, depending on the lender and your profile.Why Apply Online Instead of Visiting a Branch?The shift to digital lending in India has been driven by a few clear advantages:Speed. Online applications use digital KYC (know-your-customer) verification, automated income checks, and instant credit bureau pulls, which collapses a process that once took days into minutes.Convenience. You can apply from home, work, or anywhere with an internet connection — no need to take time off or stand in line.Transparency. Reputable digital lenders display interest rates, processing fees, and repayment terms upfront, before you commit, so you can compare offers easily.Paperless process. Most lenders now accept Aadhaar-based e-KYC and digitally signed loan agreements, removing the need for physical paperwork.Real-time tracking. You can usually track your application status, from submission to disbursal, directly through the lender's website or app.Who Is Eligible for an Instant Personal Loan?While exact criteria vary by lender, most online personal loan providers in India look at a similar set of factors:●     **Age:** Typically between 21 and 60 years at the time of application.●     **Citizenship:** Must be an Indian resident.●     **Employment type:** Salaried employees at private companies, government organisations, or PSUs, and in many cases self-employed professionals or business owners, are eligible.●     **Minimum income:** Lenders usually set a minimum monthly income threshold, which can range from around ₹15,000 to ₹25,000 depending on the city and lender, though this varies widely.●     **Credit score:** A CIBIL score of 700 or above generally improves your chances of approval and a better interest rate, though some lenders do work with applicants who have a lower or limited credit history.●     **Work experience:** Many lenders ask for a minimum period of continuous employment, often six months to a year at your current job, or a longer total work history.If you're unsure whether you meet a particular lender's criteria, most platforms, including insta-loans.com, let you check your eligibility online before you submit a full application, so it's worth doing that first.Documents You'll Typically NeedOne of the biggest advantages of applying online is how few documents are actually required. In most cases, you'll need:1.              1. **Identity proof** — Aadhaar card, PAN card, passport, or voter ID2.              2. **Address proof** — Aadhaar card, utility bill, rent agreement, or passport3.              3. **Income proof** — Last 3 months' salary slips (for salaried applicants) or the last 2 years' income tax returns and bank statements (for self-employed applicants)4.              4. **Bank statements** — Usually the last 3 to 6 months, to verify your income and spending pattern5.              5. **A recent photograph** — Often captured directly through the app during application6.              6. **PAN card** — Mandatory for loans above a certain amount, as per RBI and income tax regulationsMost lenders now allow you to upload these as scanned copies or clear photos directly within the application, and Aadhaar-based e-KYC can often verify your identity and address instantly.Step-by-Step: How to Apply for an Instant Personal Loan OnlineHere is what the typical journey looks like, from start to finish:Step 1: Check Your EligibilityBefore filling out a full application, use an online eligibility checker (available on most lending platforms) by entering basic details like your age, income, city, and employment type. This gives you an estimated loan amount and interest rate range without affecting your credit score, since it usually involves only a soft enquiry.Step 2: Compare OffersDon't apply to the first lender you find. Compare interest rates, processing fees, prepayment charges, and tenure options across a few platforms. Even a difference of 2-3% in interest rate can add up to a meaningful amount over the life of the loan.Step 3: Fill Out the Application FormOnce you've chosen a lender, you'll fill out an online form with your personal details (name, date of birth, address), employment details (employer name, monthly income, work experience), and the loan amount and tenure you're seeking.Step 4: Complete e-KYC VerificationYou'll typically verify your identity using Aadhaar-based e-KYC, either through an OTP sent to your Aadhaar-linked mobile number or a quick video KYC call. PAN verification is usually done simultaneously.Step 5: Upload Supporting DocumentsUpload your income proof and bank statements as requested. Many lenders use account aggregator frameworks or allow you to securely link your bank account for instant statement verification, which speeds up the process considerably.Step 6: Loan Approval and OfferBased on your credit score, income, and the documents submitted, the lender's system evaluates your application — often within minutes for well-qualified applicants. You'll then see the final loan offer: amount, interest rate, tenure, EMI, and any processing fee.Step 7: Accept Terms and E-Sign the AgreementIf you're happy with the offer, you accept the terms and digitally sign the loan agreement, usually via an Aadhaar-based e-signature.Step 8: DisbursalOnce everything is verified and signed, the loan amount is disbursed directly to your bank account. For many digital lenders, this happens within minutes to a few hours; for others, it may take up to 1-2 business days.Banks vs NBFCs vs Fintech Lending Apps: Who Should You Choose?Once you start comparing lenders, you'll notice that offers come from three broad categories, and each has its own strengths.Banks tend to offer lower interest rates to applicants with strong credit scores and stable, well-documented income, but their approval process can be stricter and sometimes slower, especially for self-employed applicants or those with a thinner credit file.NBFCs (Non-Banking Financial Companies) often have more flexible eligibility criteria and faster turnaround times than traditional banks, making them a good fit for first-time borrowers or those with a moderate credit score. Interest rates can be slightly higher to offset the added risk.Fintech lending platforms and apps are usually the fastest, with much of the process — application, KYC, approval, and disbursal — happening entirely within an app or website, sometimes in under 30 minutes. These are especially useful for smaller, short-tenure loans and genuine emergencies, though it's worth comparing their rates and fees carefully since convenience can come at a premium.There's no single "best" category — the right choice depends on how quickly you need the funds, your credit profile, and how much you're borrowing.Understanding Your EMI Before You BorrowBefore accepting any loan offer, it helps to understand what your Equated Monthly Instalment (EMI) actually represents: a fixed monthly payment that covers both a portion of the principal you borrowed and the interest charged on the outstanding balance. Most lenders display an EMI calculator on their website, letting you enter the loan amount, interest rate, and tenure to instantly see your monthly payment.As a general rule, financial planners suggest keeping your total EMI obligations (across all loans and credit cards combined) under roughly 40-50% of your monthly take-home income, so you have enough room for regular expenses, savings, and unexpected costs. If your EMI calculation pushes you close to or beyond that range, consider either borrowing a smaller amount or choosing a longer tenure to bring the monthly payment down — keeping in mind that a longer tenure usually means paying more interest overall.After You Apply: What Happens NextOnce your application is submitted, most lenders will keep you updated through SMS, email, or in-app notifications at each stage — application received, documents under verification, approved, and disbursed. If any document is unclear or missing, the lender will typically reach out for a resubmission rather than rejecting the application outright, so it's worth keeping an eye on your registered email and phone for any such requests.After disbursal, you'll usually receive a loan statement or repayment schedule showing your EMI due dates, outstanding balance, and total interest payable over the tenure. Setting up an auto-debit mandate (NACH) from your bank account is a simple way to avoid missed payments and the penalty charges that come with them.Is an Instant Personal Loan Right for You?An instant personal loan is a useful tool when you have a genuine, time-sensitive need and a clear ability to repay it through your regular income. It's less suited to discretionary spending that could instead be saved up for, since the interest cost adds to the overall expense. Before applying, it's worth asking yourself three simple questions: Do I need this amount urgently? Can I comfortably manage the EMI alongside my existing expenses? And have I compared at least two or three offers to make sure I'm getting a fair rate? If the answers point in the right direction, an online personal loan can bridge the gap quickly and with minimal hassle.What Affects Your Loan Approval and Interest Rate?A few factors tend to carry the most weight:●     **Credit score and credit history:** A strong, consistent repayment history on past loans or credit cards works in your favour.●     **Income stability:** A steady, verifiable income source reassures lenders that you can manage EMIs comfortably.●     **Existing debt obligations:** Lenders look at your debt-to-income ratio — if a large chunk of your income already goes toward other EMIs, it can affect how much more you're offered.●     **Employer and employment type:** Working with a well-established employer or having a longer, stable work history can sometimes improve your terms.●     **Loan amount and tenure requested:** Asking for an amount well within your repayment capacity, with a realistic tenure, improves approval odds.Tips for a Smoother, Faster Approval●     **Keep your KYC documents updated**, especially your Aadhaar-linked mobile number, since OTP verification depends on it.●     **Check your credit report in advance** and clear any small outstanding dues that might be dragging your score down.●     **Apply for a realistic loan amount** based on your income, rather than the maximum you might be offered.●     **Avoid applying to multiple lenders simultaneously**, since several hard credit enquiries in a short span can temporarily lower your credit score.●     **Double-check all details before submitting**, since mismatched information (like an address that doesn't match your documents) can cause delays.Common Mistakes to Avoid●     **Not reading the fine print:** Always check the processing fee, prepayment or foreclosure charges, and late-payment penalties before accepting an offer.●     **Borrowing more than you need:** A larger loan means a larger EMI commitment, so borrow based on your actual requirement, not the maximum eligibility shown.●     **Ignoring the total cost of the loan:** Look at the total repayment amount (principal plus interest and fees), not just the EMI, to understand what the loan actually costs you.●     **Skipping comparison:** Interest rates and fees can vary meaningfully between lenders for the same profile, so it pays to compare before committing.●     **Missing EMI payments:** Late payments can lead to penalty charges and negatively affect your credit score, making future borrowing more expensive.How insta-loans.com Can Helpinsta-loans.com is built to simplify exactly this journey — helping you understand your eligibility, compare loan options, and move through a digital application process designed for speed and clarity. Whether you're applying for the first time or comparing options against an existing offer, the goal is to give you a straightforward, transparent path from application to disbursal, with clear information on rates, fees, and terms at every step.Final ThoughtsApplying for an instant personal loan online in India today is faster and more transparent than it has ever been — but speed shouldn't come at the cost of making an informed decision. Take a few minutes to check your eligibility, compare your options, read the terms carefully, and borrow an amount that fits comfortably within your monthly budget. Done right, an online personal loan can be a genuinely useful financial tool for managing life's unplanned moments.Frequently Asked Questions1. How quickly can I get an instant personal loan online in India?For many digital lenders, approval can happen within minutes and disbursal within a few hours, provided your documents are in order and you meet the eligibility criteria. Some cases may take up to 1-2 business days depending on the lender's verification process.2. What credit score do I need for an instant personal loan?Most lenders prefer a CIBIL score of 700 or above for the best rates, but some digital lenders do consider applicants with a lower or limited credit history, often at a higher interest rate.3. Can I get a personal loan without salary slips?Yes, in many cases. Self-employed applicants can often submit income tax returns and bank statements instead of salary slips as proof of income.4. Is it safe to apply for a personal loan online?Yes, as long as you apply through a legitimate, RBI-compliant lender or a registered NBFC. Look for secure (HTTPS) websites, clear disclosure of fees and interest rates, and avoid lenders who ask for upfront payments before disbursal.5. Will checking my eligibility affect my credit score?No. Eligibility checks typically involve a soft credit enquiry, which does not impact your credit score. A full loan application, however, usually involves a hard enquiry.6. Can I prepay or foreclose my personal loan early?Most lenders allow prepayment or foreclosure after a minimum lock-in period, though some charge a prepayment fee. It's worth checking this clause before accepting a loan offer.7. What is the maximum amount I can borrow through an instant personal loan?This depends on your income, credit profile, and the lender's policies, but online personal loans in India commonly range from a few thousand rupees up to ₹5 lakh or more for well-qualified applicants.

I
Insta Loans
Oct 12, 2026 • 34 Reads

Improving Power Plant Reliability Through GE Control System Components

IntroductionPower plant reliability is essential for maintaining continuous electricity generation, operational efficiency, and equipment safety. In the turbine industry, even a minor malfunction in a control system component can affect turbine performance, interrupt power generation, or lead to costly unplanned downtime. For this reason, selecting reliable components and maintaining them according to manufacturer recommendations are important aspects of power plant operations.GE control system components are used in various industrial power generation and automation applications to support monitoring, control, and coordination of equipment. When properly selected, installed, and maintained, these components can contribute to stable turbine operation and improved plant reliability.The Role of Control System Components in Turbine OperationsTurbine control systems manage important operating parameters, including speed, temperature, pressure, vibration, and other process conditions, depending on the system configuration. They receive signals from sensors, process operating information, and coordinate control actions to keep equipment within its specified operating limits.Control system components may include control boards, input/output modules, power supply modules, communication interfaces, and other electronic assemblies. Each component performs a specific function within the overall system.Reliable components help ensure accurate signal processing, consistent communication, and appropriate control responses. In gas and steam turbine installations, these functions support safe operating practices, efficient performance, and dependable power generation.How GE Control System Components Improve Power Plant Reliability1. Consistent Monitoring and ControlReliable control components help operators monitor turbine operating conditions and respond to changing demands. Accurate signals and dependable control functions allow plant personnel to identify abnormal conditions and take corrective action before they develop into more serious problems.However, overall performance depends on the complete control architecture, component compatibility, proper configuration, and regular system testing.2. Reduced Unplanned DowntimeUnexpected equipment failures can result in production losses, emergency maintenance, and increased operating costs. Using appropriate replacement components and maintaining critical spare parts can reduce delays when repairs are necessary.A planned maintenance strategy that includes inspections, diagnostics, and timely replacement of defective components helps improve equipment availability. Keeping essential control system spares in stock can also shorten repair times.3. Improved Maintenance PlanningCondition monitoring, maintenance records, and component history help maintenance teams identify recurring issues and plan interventions more effectively. Reviewing fault logs and inspecting connections, cooling conditions, and power supplies can help detect potential problems before they affect plant operation.Maintenance activities should always follow the applicable technical documentation and plant procedures.Understanding Part Numbers in the Turbine IndustryA part number is a unique or manufacturer-defined alphanumeric identifier used to identify a specific component, assembly, or product configuration. In the turbine industry, part numbers are essential for identifying the correct control system components required for installation, maintenance, repair, and replacement.For example, a GE control card may have a part number printed on its label or listed in the manufacturer's documentation. Maintenance personnel use this identifier to distinguish the required item from other components that may look similar but have different electrical characteristics, functions, firmware, or compatibility requirements.Why Part Numbers MatterAccurate component identification: Part numbers help maintenance teams identify the intended component and reduce the risk of ordering an incorrect replacement.System compatibility: Turbine control systems may contain components with different hardware revisions or application requirements. Verifying the part number, revision, and approved compatibility information helps ensure that a replacement is suitable for the specific system.Inventory management: Power plants often maintain spare control boards and electronic modules to minimize downtime. Part numbers make it easier to organize inventories, track usage, and reorder components accurately.Maintenance documentation: Recording part numbers during inspections and replacements creates a traceable maintenance history. This information supports future troubleshooting, spare-parts planning, and maintenance audits.A part number should not be confused with a serial number. A part number generally identifies a product type or configuration, while a serial number typically identifies an individual manufactured unit. Both may be necessary when checking component history or requesting technical support.Best Practices for Selecting and Maintaining GE ComponentsPower plant operators and maintenance teams should establish clear procedures for managing control system components. Before purchasing a replacement, they should verify the part number against approved equipment documentation and confirm compatibility with the installed system.Components should be sourced through reputable suppliers and assessed for authenticity, condition, and applicable warranty or testing documentation. Where relevant, engineers should also confirm hardware revisions, firmware requirements, and manufacturer-approved substitution options.Preventive maintenance should include appropriate inspections, environmental checks, and functional testing performed by qualified personnel. Particular attention should be given to temperature, dust, moisture, vibration, electrical connections, and cooling conditions, as these factors can influence electronic component reliability.Maintenance records should document installed components, replacement dates, inspection findings, and any corrective actions taken.ConclusionImproving power plant reliability requires a combination of dependable control system components, effective maintenance practices, accurate technical documentation, and careful spare-parts management. GE control system components can support reliable turbine operations when they are correctly specified, installed, and maintained within the requirements of the relevant system.Understanding part numbers is an important part of this process. By verifying component identification and compatibility, maintaining accurate inventory records, and following manufacturer recommendations, power plant teams can reduce replacement errors, improve maintenance efficiency, and support long-term operational reliability.

G
George Philips
Oct 12, 2026 • 38 Reads

Passed Authentication? Maybe You’re Still Underinsured

The resale market for luxury goods has never been bigger, and the problem underneath it has grown: counterfeits are harder to catch. Sophisticated replicas, some aided by the same manufacturing and imaging advances available to legitimate sellers, are slipping past casual inspection and even some automated authentication tools. For anyone holding valuable handbags, jewelry, or watches, that shift has made a credentialed appraisal for insurance far more important than a simple “verified authentic” stamp ever was.Authentication Tells You It’s Real but Not What It’s WorthAuthentication and appraisal are constantly confused, but they answer entirely different questions. Authentication confirms an item isn’t counterfeit, but appraisal establishes its actual market value, condition-adjusted and documented well enough for an insurer to act on. As counterfeit detection has become a bigger focus across resale platforms, many people have assumed a “verified” badge on a listing or a third-party authentication certificate is enough to protect them. But, in reality, it isn’t because none of that documentation holds up the way a formal appraisal does when a claim is filed.Handbags: Where Counterfeit Sophistication Has Outpaced Casual InspectionDesigner handbags remain the most counterfeited luxury category by volume, and the quality of fakes has climbed sharply. Counterfeiters now closely replicate stitching patterns, hardware weight, and interior stamps, fooling not just casual buyers but also experienced resellers. This increases the risk for anyone who has purchased second-hand, inherited a piece, or hasn’t reviewed an older item’s documentation in years. Why a Handbag Valuation Still Matters Even for Authenticated PiecesA handbag valuation goes further than confirming a bag is genuine. It assesses model rarity, condition, completeness of original packaging, and current resale demand, which are the factors that actually determine replacement cost. An insurer presented with only a resale platform’s authentication certificate has no figure to work from; a handbag valuation gives them one, tied to a qualified appraiser’s name rather than an algorithm’s confidence score. The Documentation Gap That Buyers Mostly Don’t NoticeSecond-hand buyers in particular often skip this step, assuming the platform’s authentication process doubles as a valuation but, in reality, it doesn’t. Without a separate handbag valuation on file, a claim involving a resale-purchased bag can stall simply because there’s nothing beyond a purchase screenshot to establish what it was actually worth.Jewelry: Where Fakes and Undervaluation Both Do DamageJewelry carries a slightly different risk. Beyond outright counterfeits, there’s a widespread issue of stones and metals being misrepresented or simply never properly graded in the first place, especially with estate pieces, vintage jewelry, and items purchased secondhand without lab certification. Why a Jewelry Appraisal Catches What Authentication MissesA jewelry appraisal involves direct, in-hand assessment of metal purity, stone grading, and craftsmanship, which is something no online authentication process can replicate. For resale or inherited pieces especially, this is often the first time an item’s actual composition and value have ever been formally verified, rather than assumed from an old receipt or a seller’s description. The Estate and Inheritance Blind SpotA growing share of jewelry entering the resale and gifting cycle originates from estates, where original documentation has long since disappeared. In these cases, a jewelry appraisal isn’t just about insurance, but it’s often the only way to establish value for equitable division, resale pricing, or tax purposes at all.Watches: The Category Where Fraud Has Gotten the Most AttentionFew categories have seen counterfeit sophistication rise as fast as watches. High-value references have become frequent targets, with fakes now matching weight, movement sound, and even serial number formatting closely enough to pass casual inspection. Several resale platforms have responded by requiring in-house authentication before completing a sale, but this process only confirms genuineness, not insured value. Why is a watch appraisal for insurance considered a separate step?A watch appraisal for insurance considers factors such as movement condition, box and papers, service history, and current market pricing for that specific reference, which are details that a platform’s authentication check does not capture. Two watches that both pass authentication can carry very different appraised values depending on these factors, and insurers need that specificity, not just a pass/fail authenticity result. Why This Matters More for Recently Purchased Resale WatchesBuyers who purchase watches through resale channels often treat the platform’s authentication as the end of the process. It’s really the starting point. Without a formal watch appraisal for insurance purposes afterward, a buyer has proof the watch is real but no documented basis for what an insurer should pay out if it's lost, stolen, or damaged.What This Shift Means Going ForwardAs counterfeit quality continues to improve and resale volume keeps climbing, the line between “authenticated” and “properly valued” is only going to matter more. Expect insurers to lean further into requiring independent, credentialed appraisals rather than accepting a platform’s authentication badge as sufficient on its own.For anyone navigating this market, whether buying, inheriting, or simply holding onto items purchased years ago, the practical takeaway is straightforward: authentication protects against buying a fake. Appraisal protects against being underinsured for the real thing.Summing UpTo sum up, the resale boom heightened the risk of counterfeits and revealed the extent to which people confuse authentication with valuation. A handbag, jewelry, or watch appraisal for insurance each do something a verification badge can’t, which is: establish a defensible, current value that holds up when a claim actually needs to be paid. As fakes become harder to spot and resale volume continues to grow, that distinction is becoming less of a technicality and more of a necessity.

P
Prestige Valuations USA
Oct 07, 2026 • 53 Reads

Adobe Analytics to Customer Journey Analytics Migration: A Step-by-Step Guide

You rely on Adobe Analytics every day, but your customers no longer live on one website or app. They browse on mobile, call your support team, open emails and buy in stores. Adobe Customer Journey Analytics (CJA) lets you see that whole journey in one place. The move, however, needs careful planning.This guide walks you through a safe, seven-step migration. It also shows where Adobe Customer Journey Analytics consulting services save you time, money and stress.Why companies move from Adobe Analytics to CJAAdobe Analytics organizes data in report suites built for web and app tracking. CJA runs on Adobe Experience Platform (AEP) and can combine any dataset you bring into it. That shift unlocks:Cross-channel journeys: you connect web, app, CRM, call-center and offline data.Person-level analysis: you stitch devices and channels into one customer view.Flexible definitions: you define metrics and dimensions in data views, and you can change them later without re-tagging.A shared foundation: you reuse the same data for Real-Time CDP and Adobe Journey Optimizer.Adobe Analytics vs CJA: what changesAreaAdobe AnalyticsCustomer Journey AnalyticsData scopeWeb and app report suitesAny dataset in Adobe Experience PlatformData modeleVars, props and eventsXDM schemas and fieldsIdentityMainly visitor and device IDsCross-channel stitching of peopleReport setupReport suite settingsConnections and data viewsData collectionAppMeasurement or Web SDKWeb SDK, Edge Network or source connectorsThe biggest mindset change: you no longer bake definitions into collection. Your team agrees on them in the data view and documents them there.Your 7-step migration planStep 1: Audit your current setupList every report suite, eVar, prop, event, classification, segment and calculated metric. Mark what your teams actually use. Most mature setups carry years of unused variables, so retire them now rather than migrating clutter.Step 2: Define business questionsDecide what CJA must answer that Adobe Analytics cannot. Typical goals include joining CRM and web data, measuring call-center outcomes, or tracking the path from ad click to in-store purchase. Rank these use cases by business value.Step 3: Choose your migration pathYou have two main routes, and most companies use both:Analytics source connector: you bring existing report suite data into Experience Platform, so CJA can use it quickly and keep your history.Web SDK re-implementation: you move data collection to the Adobe Web SDK and Edge Network with a clean XDM schema. This takes more effort but prepares you for Real-Time CDP and Journey Optimizer.Experienced CJA migration consultants help you decide which data travels through the connector now and which you rebuild on the Web SDK.Step 4: Design schemas and identitiesMap your Analytics variables to XDM fields. Then choose the identities that will stitch people across channels, such as a CRM ID, a hashed email or a loyalty number. Get this right early, because every later report depends on it.Step 5: Build connections and data viewsCreate a CJA connection that combines your datasets. Then build data views that define metrics, dimensions, attribution settings and session rules. Rebuild your most important segments and calculated metrics as CJA components.Step 6: Run both tools side by sideRun Adobe Analytics and CJA in parallel for a period. Compare visits, orders, revenue and other key numbers. Explain every gap before you move teams over, because trust disappears quickly when numbers do not match.Step 7: Rebuild reports and train your teamsRecreate your priority Analysis Workspace projects in CJA. Then train analysts and business users on what is new, such as cross-channel reports and data view settings.Common migration mistakes to avoidYou migrate every old variable instead of cleaning up first.You skip the parallel run, so nobody trusts the new numbers.You design schemas only for analytics and ignore future CDP needs.You leave identity stitching until the end.You forget to document data view definitions.How Adobe Customer Journey Analytics consulting services reduce riskA migration touches data engineering, analytics and change management at once. Adobe Customer Journey Analytics consulting services bring proven methods for all three:Migration templates: consultants map common Analytics variables to XDM patterns they have already tested.Reconciliation checklists: they know which numbers usually differ and why.Change management: they prepare your teams, update documentation and run training.Future-proof design: they build schemas you can reuse for Real-Time CDP and Journey Optimizer.When you compare providers of Adobe Customer Journey Analytics consulting services, ask how many Analytics-to-CJA migrations they have completed and how they handle historical data.How long does the migration take?Your timeline depends on the number of report suites, the quality of your current tracking and how many new data sources you add. A simple migration with the source connector can move quickly. A full Web SDK rebuild with CRM and offline data takes longer and usually runs in phases.Final thoughtsMoving from Adobe Analytics to Customer Journey Analytics gives you the chance to clean up years of tracking debt and finally see the full customer journey. Plan in phases, run both tools in parallel, and invest early in schemas and identity. With experienced Adobe Customer Journey Analytics consulting services, you reduce risk and reach value faster.FAQsWill I lose my Adobe Analytics historical data? Not necessarily. The Analytics source connector brings report suite data into Experience Platform, so you can analyze it in CJA.Can I keep using Adobe Analytics during the migration? Yes. Most companies run both tools in parallel until the numbers match.Do I have to switch to the Web SDK straight away? No. Many teams start with the source connector and move to the Web SDK in a later phase.What do CJA consulting services include beyond migration? They usually cover measurement strategy, reporting, advanced analysis, governance and training.

A
AdobePartnerDwao